Market Note · Mortgage rates
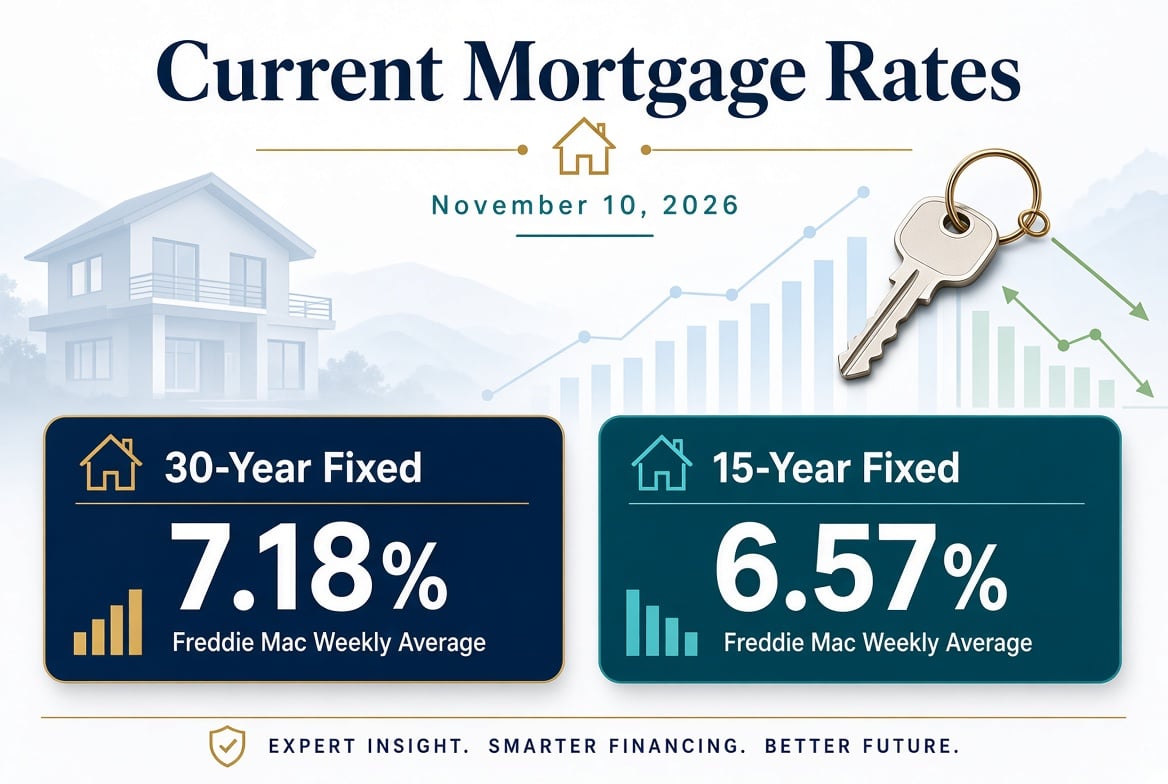
The 30-year fixed fell to 7.18% the week ending November 5, a third straight weekly decline. On a $400,000 loan, that last week is worth about $17 a month. The real change at Lake Anna is not the payment. It is that fewer people are bidding against you.
Freddie Mac's weekly survey put the 30-year fixed at 7.18% for the week ending November 5, 2026, down from 7.24% and the third weekly decline in a row. The 15-year averaged 6.57%. Before anyone gets excited: that last week of it is worth about $17 a month on a $400,000 loan. The relief is real, and it is a step back from the top of this year's range rather than a return to anything like last year's rates. The same 30-year averaged 6.22% a year ago and bottomed at 5.98% in late February, which means a $400,000 loan still costs roughly $315 a month more than it did then. The forecasters who publish rate numbers are not calling for much more improvement either. Zillow expects rates above 7% through mid-2027. What has actually changed at Lake Anna is the competition, not the payment. Purchase applications are running about 19% below last year, and pending home sales fell 10.5% year over year in October, the steepest annual drop in three years.
What that number is, and what it is not
The Freddie Mac figure is a weekly average of lender quotes across the country. It is not a rate you can lock, and we are not lenders. Nothing here is a rate quote.
Your actual number depends on your credit, your down payment, and how the house is classified. That last one matters more at this lake than most buyers expect, because most of our buyers are financing a second home, and lenders charge more for a second home than for the house you live in. If you have not run those numbers yet, what your budget actually buys at Lake Anna walks through the classifications and the loan programs. The rate illustrations in that post are from earlier this year, so use the structure and get current pricing from your lender.
Why nobody will give you a date
Mortgage rates follow the 10-year Treasury bond, not the Federal Reserve's short-term rate. When investors want a higher return to hold that bond, which is what people mean by a rising yield, mortgage rates climb with it. The 10-year yield was 4.84% midday Thursday, November 5, its lowest since early September, and that is most of why the weekly average slid.
Two things are now pulling in opposite directions. The October jobs report, released November 6, showed 165,000 jobs added against forecasts near 60,000, with unemployment down to 4.1% from 4.2%. Strong hiring usually pushes yields up, and mortgage rates follow. Pointing the other way, Realtor.com senior economist Hannah Jones has said the conflict in the Middle East has contributed to rising inflation, and that progress toward a resolution could mean lower inflation and softer mortgage rates ahead.
One timing note worth having. The 7.18% survey closed on Thursday and the jobs report landed Friday, so none of the figures above include it. The first weekly average that does comes out Thursday, November 12.
Neither of those forces has a date on it from anybody. The lenders we talk to locally are seeing the same modest relief in their pricing and are not telling anyone to count on much more of it soon. The direction over three weeks is down, the size is small, and the timeline is unknown. If somebody gives you a date, they are guessing.
Three things this changes at Lake Anna, and one it does not
- The payment, a little. About $17 a month on a $400,000 loan from the most recent week of declines, and still roughly $315 a month above where February sat.
- The size of the buyer pool. Purchase applications are down about 19% from a year ago and national home sales are near 30-year lows. Noticeably fewer people are writing offers.
- The length of the negotiation. Inventory is up year over year, and homes at Lake Anna already sit longer than they do in a suburban market. That is the part a buyer can use.
What it does not change is what sets the price of waterfront here: which side of the lake the house is on, how deep the water is at the dock when the lake drops in winter, and whether Dominion will approve the dock you have in mind. None of those move with the 10-year Treasury. The private side is Dominion's Waste Heat Treatment Facility, the cooling lagoon system that serves the North Anna station, and the six-figure gap between it and the public side has nothing to do with interest rates. Neither does a cove that goes to mud in January. Why low water might be the best buying window of the year covers how to measure that depth yourself, which is the easiest of the three to check and the one buyers most often skip.
If you are buying
The payment is the part you can change later. The house is not. You can refinance a rate. You cannot refinance a cove.
If you are paying cash or putting a large amount down, the rate matters less to you than to almost anyone else shopping right now, while the thinner buyer pool matters to you just as much. Pending sales are down 10.5% from last October, and that figure counts cash purchases too. Fewer buyers are in line for the same waterfront in Louisa, Spotsylvania, and Orange counties, whether or not you are financing.
If you are selling
Your buyer pool is smaller and more serious. The people still shopping in November at 7% are not browsing.
In a market like this one, terms usually do more than another price cut. A rate buydown, where you pay the lender up front to lower the buyer's rate, plus a closing credit, a flexible closing date, or leaving the boat lift, tend to cost a seller less than the next round off the price, and they go straight at the monthly payment, which is where a financed buyer is actually stuck. How to price your Lake Anna home covers the trade between price and days on market if you are deciding whether to adjust.
Frequently asked questions
What is the mortgage rate at Lake Anna right now?
There is no Lake Anna rate. Lenders price nationally and then adjust for your file. The national benchmark is Freddie Mac's weekly survey, which put the 30-year fixed at 7.18% and the 15-year at 6.57% for the week ending November 5, 2026. Your quote at Lake Anna will usually land above the 30-year headline number, because most purchases here are second homes rather than primary residences, and lenders charge more for a second home. Get a quote from a lender rather than working off a survey average.
Are mortgage rates going down in 2027?
Nobody knows, and the forecasters who publish numbers are not expecting a large move. Zillow expects rates to stay above 7% for the rest of 2026 and through mid-2027. The 30-year averaged 7.18% for the week ending November 5, 2026, down three weeks running, but it was 6.22% a year ago and 5.98% in late February, so the recent decline is a retreat from the top of the year's range. Plan a Lake Anna purchase on a payment you can carry at today's number, and treat any improvement as a refinance you might get later.
Does a second home at Lake Anna have a higher mortgage rate than a primary residence?
Usually yes. Lenders classify a property as a primary residence, a second home, or an investment property, and the pricing gets worse at each step. Most Lake Anna buyers are in the second-home tier, which typically means a larger down payment and a higher rate than the headline 30-year average you see quoted in the news. If the plan is to rent it out part of the year, tell your lender before you write the offer, because the classification can change and so can the terms. Short-term rental rules at Lake Anna also vary by county and by HOA covenant, so confirm both.
Should I wait for lower rates to buy at Lake Anna?
That depends on what you are trading away while you wait. Rates can be refinanced. A specific house on a specific cove cannot. Right now purchase applications are down about 19% from a year ago and pending sales fell 10.5% in October, which means fewer buyers in line for the same waterfront. If you wait for a lower rate and it arrives, you will be shopping against everyone else who also waited. The question to answer is not whether rates will fall. It is whether the house you want will still be there, and still be worth what you would pay for it, when they do.
Is now a bad time to sell a Lake Anna lake house?
It is a slower time, not a dead one. Pending home sales fell 10.5% year over year in October and inventory is up, so a seller should expect a longer marketing period and a more deliberate buyer. What has not changed is that waterfront at Lake Anna is priced on things interest rates do not touch: the side of the lake, the depth at the dock when the lake drops in winter, and whether the shoreline and dock are in approvable condition. Sellers who compete on terms, including a rate buydown or a closing credit, generally do better in this market than sellers who take another round of price cuts.
Where these numbers came from, and when. Rate averages are Freddie Mac's Primary Mortgage Market Survey for the week ending November 5, 2026, with the year-ago and February figures from the same survey. Payment comparisons are our own arithmetic on a $400,000 30-year loan at those rates, principal and interest only. The 10-year Treasury yield is from midday Thursday, November 5. Purchase applications, pending home sales, inventory, and the note that national home sales are near 30-year lows come from the Mortgage Bankers Association, Realtor.com, and Zillow as reported the week of November 2, 2026. Employment figures are the Bureau of Labor Statistics October report released November 6, 2026. The Zillow expectation and the Hannah Jones comments were published the week of November 2, 2026. That Lake Anna homes sit longer than suburban listings is our own observation from working this market, not a published statistic. Freddie Mac updates the survey every Thursday, so any of these can move. Check the current figure before you make a decision on it.
What we are and are not. The M Group is a real estate brokerage. We are not a mortgage lender, a mortgage broker, or a licensed loan originator. Nothing here is a rate quote, a loan offer, a commitment to lend, or our prediction of where rates will go. Where this post reports an expectation about rates, it names who said it. Rates vary by borrower, by property classification, and by lender, and the only number that matters to your purchase is the one a lender puts in writing for you.
Trying to decide whether this changes your timeline?
Send us a specific address and we will run the real numbers on it: the payment at a second-home rate, what that cove looks like when the lake drops in winter, and what comparable homes on that side of the lake have closed at this fall.
Talk to us about buying at Lake Anna, or get a straight answer on what your waterfront is worth.
No obligation and no pressure either direction. If the answer is wait, we will tell you to wait.
Michael Boyce II, Real Estate Professional
The M Group, Real Broker, LLC
540-870-0437
[email protected]
www.themgroupva.com
Melanie Lucero, Real Estate Professional
The M Group, Real Broker, LLC
540-870-0714
[email protected]
www.themgroupva.com
Related reading
Can You Afford a Lake Anna Home?
Why Low Water at Lake Anna Might Be the Best Buying Window of the Year
How to Price Your Lake Anna Home
Want the lake in your inbox? The Lake Life Briefing goes out weekly with lake levels, what is happening around the water, and new listings. Sign up here.
